Why Every Crypto Wallet Is Turning Into a Bank in 2026
 October 9, 2026
7 min read
Disclosure: This article is analysis and opinion, not financial advice. Figures are cited from 2026 industry reports and change. See our full disclaimer.
Six months ago, your crypto wallet held keys. Today, a growing number of them hold your savings, issue their own dollars, pay you yield, and hand you a card to spend it all. The wallet quietly turned into a bank while nobody called it that out loud.
This isn’t one company’s bet. It’s happening across the whole industry at once, from two directions, and the pattern is clear enough now to name.
The evidence, in receipts
Count the launches from the last few months. MetaMask shipped Money Account, a self-custodial balance paying ~4% on its own stablecoin, mUSD. Phantom did the same with CASH behind its debit card. Tether launched a self-custodial wallet in April 2026. Telegram split off Walt, a trading platform, from its billion-user wallet. And a wave of dedicated crypto cards (Bleap, Gnosis Pay, Plasma One) made spending stablecoins routine.
The numbers back the vibe. Crypto neobank card volume jumped 223.5% in early 2026, and the crypto wallet market is projected to grow from $19.3 billion in 2026 to $100.8 billion by 2033. A wallet in 2026 can stake, swap across chains, earn yield on idle stablecoins, buy coffee with a card, and trade perpetual futures. That used to be five apps.
Why it’s happening now
Three things lined up. Stablecoins matured into a settlement layer reliable enough to build banking products on, and the US GENIUS Act gave wallet-issued dollars a federal framework to stand on. Fast, cheap chains (Monad, Base, Solana, and the payment-specific ones) made real-time card authorization actually work. And the business pressure got real: with hundreds of wallets fighting for the same users, “just storing keys” stopped being a product. The wallet that also pays yield and hands you a card wins the daily open.
The convergence runs both ways, which is the part that makes it structural rather than a fad. From the other side, neobanks are adding crypto: Revolut now runs its own exchange and is MiCA-licensed across 30 EEA markets, and N26 offers 400+ tokens through Bitpanda. The crypto wallet is becoming a bank at the same moment the bank is becoming a crypto wallet. They’re meeting in the middle, and the meeting point is a stablecoin balance with a card attached.
What a 2026 “wallet” actually does now
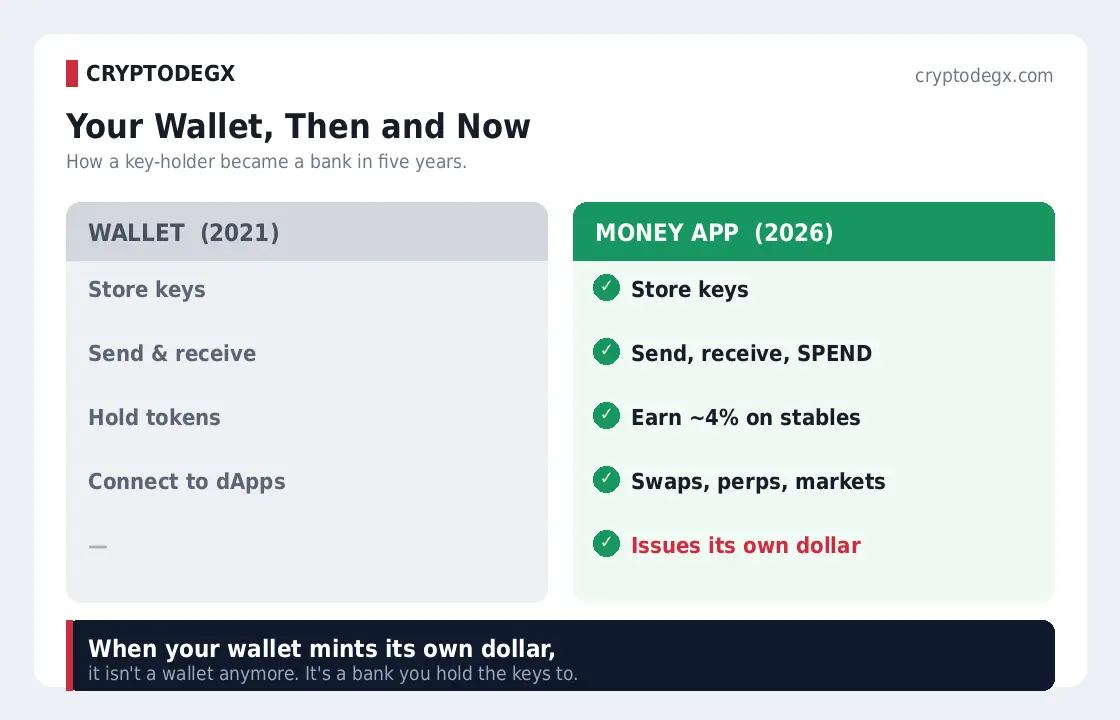
| Old wallet (2021) | New wallet / money app (2026) |
|---|---|
| Store private keys | Store keys, still self-custodial |
| Send and receive crypto | Send, receive, and spend via card |
| Hold tokens | Hold tokens + earn ~4% on idle stablecoins |
| Connect to dApps | Native swaps, perps, prediction markets |
| (nothing) | Issue its own branded stablecoin (mUSD, CASH) |
That last row is the quiet giveaway. When your wallet mints its own dollar, it isn’t a wallet anymore in any meaningful sense. It’s a financial institution with a consumer app, holding deposits (in stablecoin form) and paying interest on them. The word “bank” is doing real work there.
The skeptic’s case, which deserves airtime
Not everyone thinks this ends well, and the bear argument is sharp. The warning, made bluntly in a crypto.news opinion piece: wallets copying the zero-fee-card playbook are inheriting a business model that already failed in fiat. Card interchange is capped, FX spreads are vanishing, and crypto cards stack blockchain costs on top of card-rail overhead. The margins are thin going to negative.
The counterargument from the wallets is that the card is a loss leader, the front door, and the real money is in what you do once inside: swaps, yield spreads, perps, tokenized assets. Maybe. But that assumes users who came for a free card and 4% yield will stay to trade at a margin, and plenty of fiat neobanks made that same bet and are still waiting for it to pay off. Whether crypto’s version breaks the pattern or repeats it is genuinely unsettled, and worth watching with a cold eye.
Where this goes
The term “crypto wallet” is probably on its way out, and so is “neobank.” When every fintech offers stablecoin features and every serious crypto app looks like a bank, the categories collapse into one: a money app that happens to run on blockchain rails, self-custodial if you’re lucky, that you spend from, earn in, and trade through.
For the industry, that’s arguably the most real adoption milestone yet, more concrete than any ETF. For you, it’s a shift that rewards paying attention: the convenience is real and worth using, the risks moved rather than vanished, and knowing which wallet-bank actually holds your keys is the whole game. We’re reviewing them one at a time in the reviews section for exactly that reason.
FAQ
Are crypto wallets really becoming banks?
Functionally, yes. Major wallets now offer the core services of a bank: a dollar balance (via stablecoins), interest on deposits (DeFi yield of around 4%), a debit card to spend, and in-app trading. MetaMask, Phantom, and others have even launched their own branded stablecoins. The main difference from a real bank is that the best ones stay self-custodial, so you keep control of your keys.
What is a crypto neobank or wallet super app?
A single app that combines what used to take several: holding crypto, earning yield on stablecoins, spending via a card, and trading, all in one balance. The term covers both crypto wallets adding bank-like features (MetaMask, Phantom) and fintech neobanks adding crypto (Revolut, N26). The categories are merging into one “money app” model.
Is keeping money in a wallet-bank safe?
It depends on the model and your use. Self-custodial wallet-banks remove the risk of a company freezing or losing your funds, which is a real advantage. But the yield comes from DeFi lending rather than an insured deposit, stablecoins can depeg, and newer chains carry more risk, so these suit active-use funds rather than emergency savings. There’s no deposit insurance.
Why are wallets adding yield and cards in 2026?
Competition and opportunity. With hundreds of wallets fighting for daily active users, simply storing keys no longer differentiates anyone, so wallets add yield and cards to become the app you open every day. Maturing stablecoins, faster chains, and the US GENIUS Act’s stablecoin framework made these features practical to ship at the same time.
Do wallet-banks pay better interest than real banks?
Roughly comparable, around 4% on stablecoins versus about 4-5.5% at the best neobanks like Revolut’s Metal tier. The difference is the source and the protection: bank interest comes with deposit insurance and regulation, while wallet yield comes from DeFi lending with neither. Similar rate, very different risk underneath.
Will “crypto wallet” stop being a useful term?
Likely. As every fintech adds stablecoin features and every major crypto app adds bank-like ones, the distinction between a wallet, a neobank, and a trading app keeps dissolving. The emerging category is simply a money app running on blockchain rails, and the labels from crypto’s earlier era describe it less and less well.
What’s the risk that this trend fails?
The economics. Critics note that zero-fee cards and thin stablecoin margins mirror a neobank model that struggled in fiat, with interchange capped and FX spreads shrinking. The bet is that free cards and yield are a front door to higher-margin trading and RWA products, but that assumes casual users convert to active traders, which fiat neobanks have found harder than expected.