Bleap Card Review (2026): The Stablecoin-Cashback Card, Honestly
 October 7, 2026
8 min read
Disclosure: This review is information and opinion, not financial advice. Figures are as of late 2026 and change; confirm current rates and availability before applying. See our full disclaimer.
Bleap gets one big thing right that almost no other crypto card does: it pays your cashback in USDC, a stablecoin, instead of a volatile reward token you have to hold and watch. After reviewing Gnosis Pay (cashback in GNO) and Plasma One (cashback in XPL), that single design choice is genuinely refreshing.
But Bleap’s marketing leans hard on “up to 20% cashback,” and that number deserves a hard look, because it’s real and it’s mostly a mirage at the same time. Here’s the honest read.
What Bleap is
Bleap is a free, self-custodial Mastercard debit card that spends your crypto directly, with cashback paid in USDC. It’s issued through a regulated European e-money institution (Unlimit, Cyprus), runs on account-abstraction smart wallets, and lets you spend from a wide range of tokens across chains like Base, Polygon, Arbitrum, and Solana, converting to fiat at the point of sale.
The pitch is “spend crypto like cash, keep your custody, get paid in a currency that doesn’t swing.” For the right spender, it delivers exactly that.
| Type | Self-custodial Mastercard debit |
| Custody | Account-abstraction smart wallet (you control) |
| Cashback | 1% to 20% tiered, paid in USDC |
| Card fee | Free (no issuance, monthly, or subscription) |
| FX fee | 0% |
| Networks | Base, Polygon, Arbitrum, Solana and more |
| Issuer | Unlimit EU (regulated EMI, Cyprus) |
| Availability | EEA, expanding to Latin America |
The cashback, honestly: where “20%” comes from
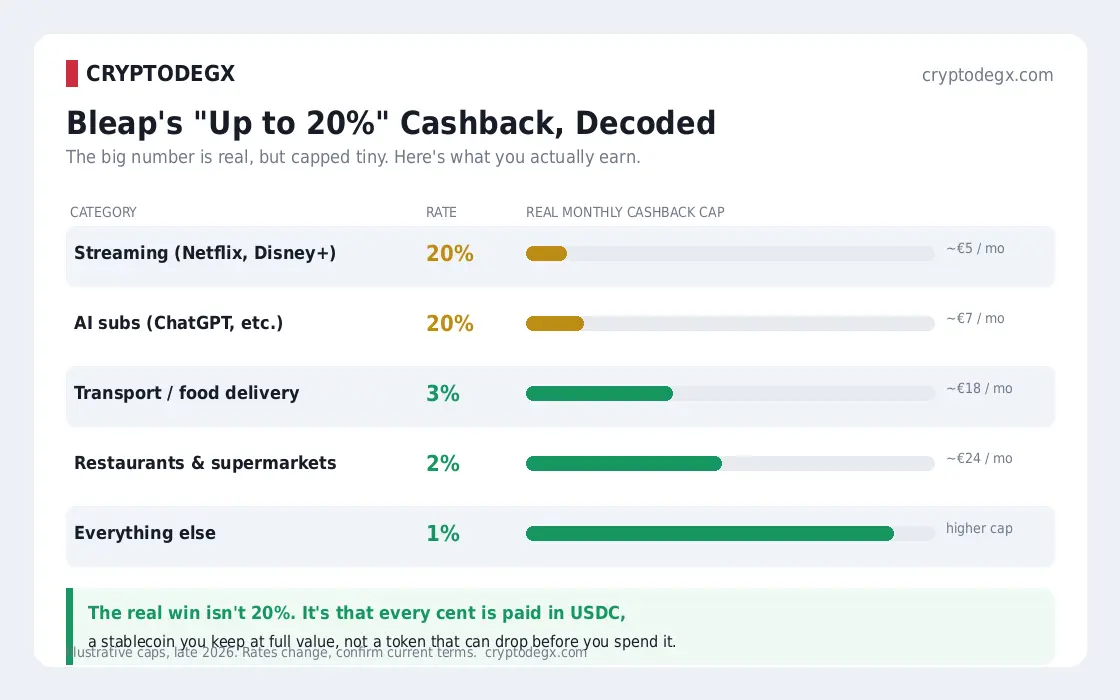
This is the section the Bleap-published reviews skip, so let’s be precise. The cashback is tiered by spending category, and the eye-catching rates come with small monthly caps:
| Category | Cashback | Rough monthly cap |
|---|---|---|
| Streaming (Netflix, Disney+) | 20% | ~€5 |
| AI subscriptions (ChatGPT, etc.) | 20% | ~€7 |
| Transport / food delivery | 3% | ~€18 |
| Restaurants & supermarkets | 2% | ~€24 |
| Everything else | 1% (up to 2%) | higher / fair-use |
So the “20%” is real, but it tops out around €5-7 a month because the cap is tiny. Add every category’s cap together and the maximum cashback a normal person can realistically earn lands in the low tens of euros monthly, most of it from the 1-3% everyday tiers, not the headline 20%. That’s not a scam; it’s standard cashback-marketing math. It does mean you should ignore the 20% and judge Bleap on its 1-3% real-world rate, which is still solid, and paid in stable USDC.
Fees: genuinely close to zero
This is Bleap’s strongest, least-asterisked area. No issuance fee, no monthly or annual fee, no subscription, 0% FX on any currency, and no conversion-fee markup when the card converts your stablecoin to fiat at the till. For someone who travels or spends across currencies, that 0% FX alone beats most custodial cards, which quietly charge 0.5-2% on foreign spend.
The honest caveats: ATM access is limited (it’s a card-first product, not a full banking replacement), and because it spends from crypto, you’re subject to the usual on-chain realities when funding, like network fees if you bridge in from the wrong chain, per the network-matching basics.
Self-custody: real, but a different flavor
Bleap is self-custodial, with a wrinkle worth understanding. Instead of a traditional seed-phrase wallet, it uses account abstraction / MPC (multi-party computation), meaning there’s no single seed phrase you write down; the signing power is split cryptographically. You still control your funds (Bleap and the issuer can’t spend them, and funds stay yours until the moment of purchase), but the security model differs from a classic hardware-wallet setup.
The upside: no seed phrase to lose, easier onboarding. The trade-off: you’re trusting the MPC implementation and the app rather than holding a single key yourself, which is a more convenient but less purist form of self-custody than, say, spending from your own hardware wallet. Worth knowing which you’re getting.
Bleap vs the other self-custody cards
| Feature | Bleap | Gnosis Pay | Plasma One |
|---|---|---|---|
| Cashback paid in | USDC (stable) | GNO (volatile) | XPL (volatile) |
| Real everyday rate | 1-3% | 1-3% (by GNO held) | 2-4% (stepped) |
| Token to hold / lock | None ✓ | Hold GNO | Hold / lock XPL |
| Built-in yield | Savings vault ~3.8% AER | None | Earn vault ~4% |
| Fees | Free, 0% FX | ~€30 once, 0% FX euro | Tier fees, 0-1% FX |
| Network | Mastercard, multi-chain | Visa / Gnosis Chain | Visa / Plasma chain |
| Availability | EEA, LatAm expanding | EEA + UK | 150+ (not US) |
The read: Bleap wins on reward quality (stable USDC, no token to babysit) and on fees (truly free, no tier to unlock). Gnosis Pay is the euro self-custody benchmark but ties rewards to GNO; Plasma One adds a yield vault but wraps everything in the volatile XPL loop. If you just want a free card that pays you in dollars and keeps you in custody, Bleap is the simplest answer of the three.
What Trustpilot and real users flag
A balanced review includes the complaints. Across user reviews, the recurring themes are: occasional onboarding and verification delays, support response times that can lag during busy periods, and the cashback caps catching people who expected the 20% to apply broadly. The product itself (spending, cashback payout, custody) generally works as described; the friction tends to be around support and expectation-setting rather than lost funds. As with any newer fintech, treat it as a spending card rather than your only account, and keep the bulk of your holdings in your own primary wallet.
Who it’s for, who it isn’t
Get it if
- You want cashback in stable USDC, not a token
- You’re in the EEA and spend across currencies
- You want a genuinely free, no-subscription card
- You value self-custody but want easy onboarding
- You spend on streaming / AI subs (real 20% there)
Skip it if
- You’re outside its regions (US included)
- You believed the 20% applies to all spending
- You want a purist hardware-wallet custody model
- You need strong ATM / full-banking features
- You want the highest headline number on paper
FAQ
Is the Bleap card worth it?
For EEA spenders who want self-custody and cashback in stable USDC rather than a volatile token, yes: it’s free, charges 0% FX, and pays rewards you can keep without watching a token price. Just judge it on the real 1-3% everyday rate, not the 20% headline, which only applies to small monthly caps on streaming and AI subscriptions.
Is the 20% Bleap cashback real?
It’s real but capped tightly: 20% applies only to streaming and AI subscriptions, maxing out around €5-7 per month each. Most of your actual cashback comes from the 1-3% everyday tiers. Treat 20% as a marketing headline and expect a blended real rate in the low single digits, paid in USDC.
How does Bleap cashback get paid?
In USDC, automatically credited to your on-chain balance once a transaction settles. Because it’s a stablecoin, the reward holds its dollar value rather than swinging with a token price, which is Bleap’s main advantage over cards that pay cashback in their own volatile token.
Is Bleap really self-custodial?
Yes, though via account abstraction and MPC rather than a traditional seed phrase. Your funds stay under your control and aren’t held by Bleap or its issuer until the moment you spend, but the security model relies on multi-party computation rather than a single private key you store yourself. It’s convenient self-custody, not purist hardware-wallet custody.
What fees does Bleap charge?
Effectively none on the basics: no issuance, monthly, or subscription fee, 0% FX on any currency, and no conversion markup at the point of sale. The realistic costs are on-chain network fees when funding from another chain and limited ATM functionality, since it’s designed as a spending card rather than a full bank account.
Which countries support Bleap?
It’s available across the EEA and is expanding into Latin America, issued through a regulated European e-money institution. It is not available in the US. Confirm current country coverage on the official site before applying, since fintech availability shifts.
Bleap vs Gnosis Pay vs Plasma One?
Bleap pays cashback in stable USDC with no token to hold and a free card; Gnosis Pay pays in GNO and is the euro self-custody benchmark; Plasma One pays in XPL but adds a yield vault. For the simplest stable-reward self-custody card, Bleap; for euro-focused custody, Gnosis Pay; for an integrated yield vault, Plasma One.
Is Bleap safe?
Its custody design keeps funds in your control, so there’s no company balance to freeze or lose, the failure mode behind most exchange collapses. The issuer is a regulated EMI. The main caveats are reliance on the MPC implementation, newer-fintech support friction noted in user reviews, and the usual practice of keeping only spending money on any card rather than your whole portfolio.